Distribution Day And Dollar Decline Puts Cloud Over Rally
The
decline in the dollar was the big story over the latest week, and as
the dollar declined, the market took it on the chin, with the averages
registering a distribution day. The highs
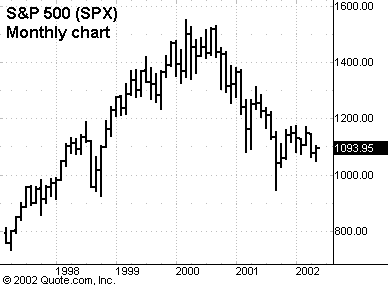
of this week came off of Fibonacci resistance levels in the S&P, so we have
a real tug-of-war technically between this week’s highs and last week’s
lows. Whichever of these the indexes all
take out will probably determine the next short-term move.
The dollar index is also
getting near 111 support and is likely to consolidate at least somewhere from
current levels to this level, easing pressure on the market somewhat.
A sharp decline by the nearby dollar futures below 111 would not be good
news for the market if it occurs in short-order.
The Fed will let the dollar decline particularly as the economy is
weakening in its recovery phase, and a weaker dollar is stimulus that the Fed is
running out of room on with interest rates so low.
But investors need to monitor closely whether the dollar is declining in
an orderly fashion, or a route is developing.
Commodities, gold, commodity
currencies, economically sensitive commodities, and strength or weakness in EM
Asia and EM Eastern Europe are all markets that will help investors gauge
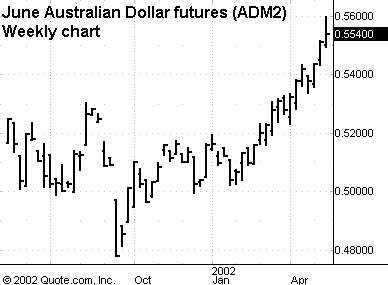
whether the recovery is in jeopardy or not. Right
now with gold and the commodity currencies rallying, the markets are not
discounting any return to a global recession. As
long as gold, the NZD
and AUD, the economically sensitive
commodities (oil, cotton,
copper, lumber,
bond yields), and EM stock prices and
economic releases all hold up, the odds of a return to deflation/recession
remain very low. Should the majority of
these markets start to turn, THAT would be a clear warning sign that the global
recovery scenario is being challenged significantly, and a new wave down in
global stock prices would become a much stronger likelihood.

Our odds-favorite scenario
continues to be a LONG trading range in developed
markets, similar to the environment of 1965-1982, with intermittent mini-bull
and mini-bear moves for the next five-plus-years.
EMs MAY be launching a secular bull market
that would be much more profitable and playable.What the U.S. market needs now
is more evidence of earnings fuel — more evidence of
broad-based earnings gains so that earnings gains can begin to take over
from monetary stimulus as the fuel behind stock price gains.
But so far it has been relatively profitless for U.S. companies.
We need better earnings news and much stronger breadth numbers and
rallies by market leaders, not just bounces from stocks approaching old lows.
[banner]
Watch for breadth and leadership before anticipating any kind of real
rally developing — and then only expect a potential MINI
bull move — playable, but nothing like the bull moves of the 1982-2000 secular
bull markets.
In the meantime, our US
long/short strategy continues to show reasonable gains with very low risk this
year, although we got whipped a bit in America’s CarMart
(
CRMT |
Quote |
Chart |
News |
PowerRating) last week.
We’re making money at close to a 20% rate so far this year, OK, but not
exactly wonderful. Investors may have to
adjust to a lengthy period of global multiple convergence, where overvalued U.S.
stocks have trouble rallying en masse for many years, while certain sectors
present limited but good opportunities, such as we’ve seen in the homebuilding
industry this year. And while our
strategy profit is decent, it isn’t as large as those investors who have taken
our suggestion and ventured into the Emerging Markets — where we suspect most
of this year’s gains will be made. We
are particularly partial to the China region now, which has just begun a
self-reinforcing recovery.
Top
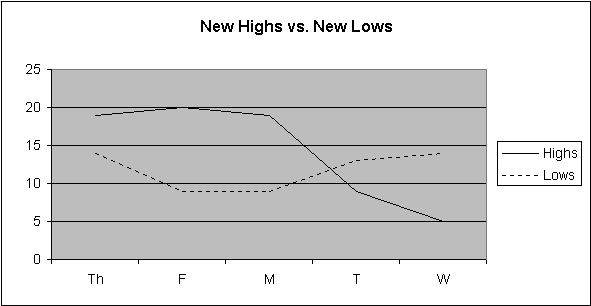
RS/EPS New Highs this past week were 19,
20, 19, 9 and 5 — showing more deterioration than we’ve seen in many weeks.
We had one valid trade in CRMT which broke out and promptly stopped us
out for a whipsaw trade, but only five breakouts on our list for the week.
We need more quality leadership for this rally to take hold, along with MUCH
broader participation. Bottom
RS/EPS New Lows expanded slightly this week, but remain far below 20
consistently, with 14, 9, 9, 13 and 14
readings, and only three breakdowns with no real close calls.
Right now opportunities on both the long and short sides are scarce, but
we are being spared a lot more whipsaw trades that are occurring in other
methods.
Our overall allocation remains
ULTRA DEFENSIVE. We’re now 100% in
T-bills (including short-sale proceeds) awaiting new opportunities. Our model
portfolio followed up weekly in this column was up 41% in 1999, up 82% in 2000
and up 16.5% in 2001 — all on a worst drawdown of around 12%. We’re
now up around 7% for the year 2002, mainly driven by a select couple of names,
which is often the case in a market that is searching for leadership. Due to
the volatile nature of the U.S. market, we will probably see more frequent and
larger drawdowns than we’ve had so far, if we can ever get to the point of
more aggressive allocation that is.
For those not familiar with our
long/short strategies, we suggest you review my 10-week
trading course on TradingMarkets.com, as well as in my book The
Hedge Fund Edge, course “The Science of Trading,” and new
video seminar most of all, where I discuss many new techniques. Basically,
we have rigorous criteria for potential long stocks that we call
“up-fuel,” as well as rigorous criteria for potential short stocks
that we call “down-fuel.” Each day we review the list of new highs on
our “Top RS and EPS New High List” published on TradingMarkets.com for
breakouts of four-week or longer flags, or of valid cup-and-handles of more than
four weeks. Buy trades are taken only on valid breakouts of stocks that also
meet our up-fuel criteria. Shorts are similarly taken only in stocks meeting our
down-fuel criteria that have valid breakdowns of four-plus-week flags or cup and
handles on the downside.
In the U.S. market, continue to
only buy or short stocks in leading or lagging industries according to our group
and sub-group new high and low lists. We continue to buy new signals and sell
short new short signals until our portfolio is 100% long and 100% short (less
aggressive investors stop at 50% long and 50% short). In early March of 2000, we
took half-profits on nearly all positions and lightened up considerably as a sea
change in the new-economy/old-economy theme appeared to be upon us. We’ve been
effectively defensive ever since.
Upside breakouts meeting
up-fuel criteria (and still open positions) so far this year are:
Group 1 Automotive [GPI|GPI] @44.84 —
out on 45 ops. Continue to watch our NH
list and buy flags or cup-and-handle breakouts in NH’s meeting our up-fuel
criteria — but be sure to only add names that are in leading groups, and now
only add two trades per week once again until the market environment improves.
On the short side this year,
we’ve had breakdowns from flags (one can use a down cup-and-handle here as well)
in stocks meeting our down-fuel criteria (and still open positions) in: Mediacom
Communications
(
MCCC |
Quote |
Chart |
News |
PowerRating) @10.54 — out on 12 ops. Continue to
watch our NL list daily and to short any stock meeting our down-fuel criteria
(see 10-week
trading course) breaking down out of a downward flag or down
cup-and-handle that is in a leading group to the downside, but only add up to
two in any week until market weakness is more pronounced.
Traders and investors now need
to stay lean, mean, and watching the broad markets like a hawk.
Watch the plurality of the markets in general for clues on how to move
next. Further indication of recovery will
show up in commodity prices and further rallies in developed markets, giving EMs
a further push. Deflationary and
inflationary scenarios also need to be monitored.